Venture Capital's Paradox: Record Spending Masks Shrinking Deal Flow
Despite nearly $680 billion in venture funding through Q3 2026, investors are writing far fewer checks to early-stage companies, concentrating capital in mega-rounds while seed and Series B deals plummet.
The venture capital market presents a striking contradiction in 2026: funding totals have reached historic highs, yet the number of companies receiving investment continues to decline. Crunchbase data reveals this tension has intensified through the third quarter, exposing a fundamental shift in how capital flows through the startup ecosystem.
Venture investors deployed nearly $680 billion through Q3 2026, a record amount. Yet this abundance masks a troubling reality for most founders: investors are backing fewer deals, particularly at the seed and early stages where most startups begin their journey.
Large rounds dominate funding
The concentration of capital becomes clear when examining where the year's record funding actually went. Rounds exceeding $1 billion have surged dramatically, while deals under $100 million have essentially stalled since 2023.
The spike in mega-rounds during the first half of 2026 was driven largely by record-setting financings for OpenAI and Anthropic. However, these two companies do not account for the full picture. In Q3 alone, approximately one-third of all venture funding went to just 27 companies closing billion-dollar-plus rounds.
Deals keep falling even as dollars rise
North America, the world's largest startup market, illustrates this divergence most clearly. Deal counts have declined steadily over multiple years even as total venture investment has climbed.
In Q3, North American deal counts fell 16 percent year over year and 14 percent quarter over quarter, marking the lowest quarterly total since 2023. Meanwhile, funding dollars in the region jumped 50 percent year over year to $92 billion. The decline is concentrated in seed and early-stage transactions; late-stage deal counts actually increased compared to the prior year.
The early-stage slump
Series B funding exemplifies the dollars-up-but-deals-down dynamic most starkly. This stage represents a critical juncture where startups demonstrate initial growth and market traction while retaining substantial upside. Yet despite dollars invested in U.S. Series B rounds reaching multiyear highs in 2026, deal counts are tracking toward multiyear lows.
Seed and Series A rounds follow the same pattern, with capital concentrating into larger individual rounds while the total number of deals shrinks.
Looking ahead
Anthropic, the largest venture-backed private company, is scheduled to go public this month in a potential $2 trillion IPO. The outcome will serve as a significant indicator of how public markets view the companies fueling the current venture boom.
A successful public debut could strengthen venture investors' conviction to fund massive AI bets, while a weak reception could pressure unicorn valuations. Neither scenario, however, ensures that capital will flow more broadly to the wider startup ecosystem.
The true test of a genuine startup recovery will be whether deal counts begin rising alongside funding dollars. Until that happens, the venture market remains bifurcated: abundant capital for the few, scarcity for the many.
Read more
Data Authority: The Hidden Lever CIOs Need to Reduce Cyber Risk
As exploit windows shrink to hours, organizations face a new bottleneck: decision latency. CIOs who establish trusted data authority can move from managing uncertainty to managing measurable risk reduction.
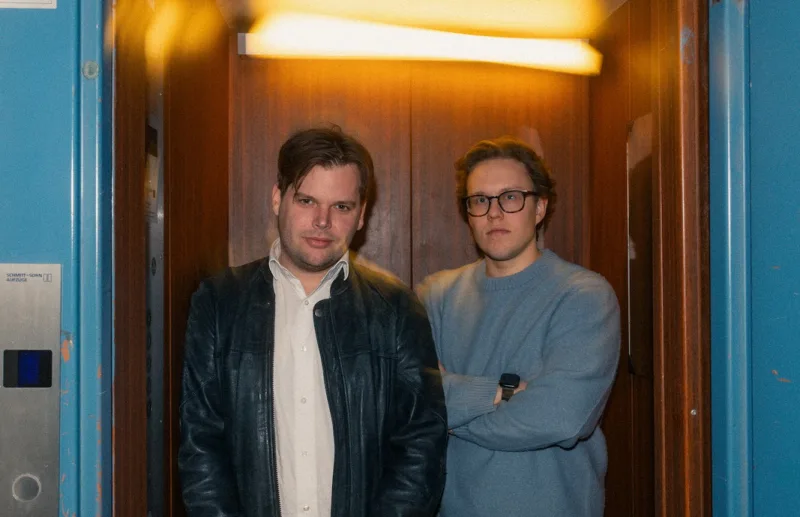
Marble Cognition Lands $3.75M to Teach AI Agents How Employees Actually Work
The Munich startup has developed technology that observes and records worker behavior to create process maps that AI agents can learn from and automate, addressing a critical gap in enterprise AI deployment.
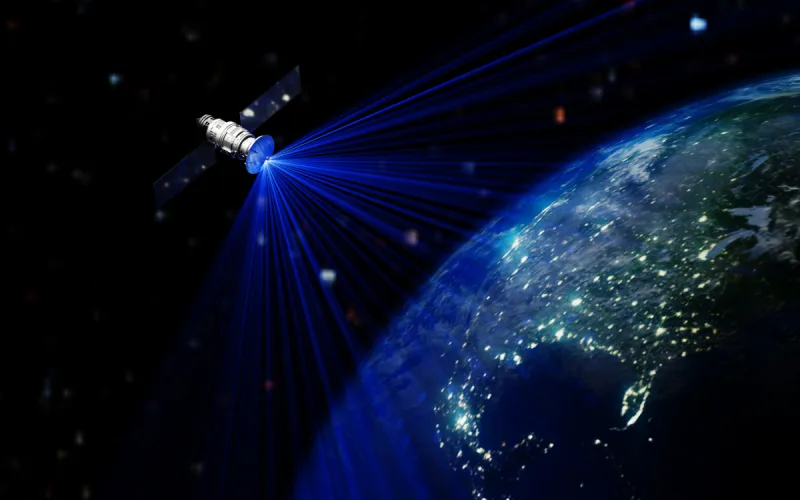
Satlyt Demonstrates Distributed Computing Across Orbiting Satellites
The startup has successfully tested software that orchestrates computing tasks across multiple spacecraft in orbit, moving closer to its vision of turning satellites into networked data processing hubs.