How This Norwest Investor Tests a Founder's Sales Chops Before Writing a Check
Sean Jacobsohn, a partner at Norwest Venture Partners, brings a rare sales background to venture investing. Before committing capital, he personally joins sales calls to evaluate whether a CEO can actually sell.
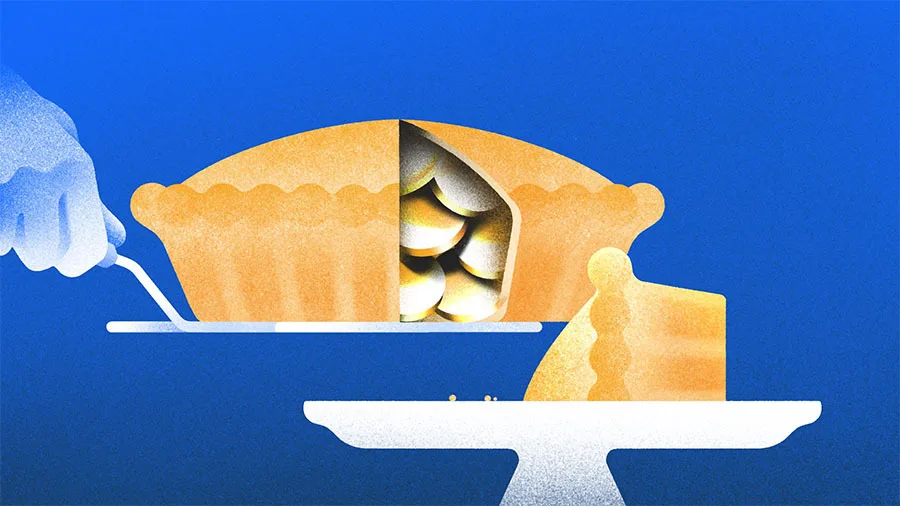
Sean Jacobsohn's path to venture capital ran through the operational trenches of enterprise software. During his time at WageWorks and Cornerstone OnDemand, he witnessed both companies scale from low single-digit millions to tens of millions in revenue. His tenure also included a stint at Upwork. All three organizations eventually went public. Following these operational roles, Jacobsohn spent time as a venture partner at Emergence Capital before arriving at Norwest in 2014.
At the Menlo Park-based Norwest, Jacobsohn concentrates on enterprise software investments, leveraging expertise spanning finance, sales and business development. His current portfolio encompasses 15 active companies, ranging from pre-revenue ventures to mature businesses generating north of $300 million annually. Finance and HR software dominate his holdings, though he also deploys capital in supply chain and construction technology, particularly where companies are building financial tools for those sectors.
The unifying theme across his investments centers on next-generation applications displacing entrenched incumbents that have failed to modernize. Finance has proven especially attractive territory, given that buyers already maintain dedicated software budgets and numerous categories remain controlled by outdated platforms.
Norwest itself, established in 1961, oversees $15.5 billion in assets and currently deploys capital from its 17th fund, a $3 billion pool closed in 2024. The firm has backed more than 700 companies spanning enterprise, consumer and healthcare sectors globally.
Where Finance Software Still Has Room to Grow
Despite the crowded landscape of finance applications, Jacobsohn identifies persistent opportunities in replacing legacy systems. His Office of the CFO market map contains more than 500 companies, with roughly three-quarters representing established players ripe for disruption.
A structural advantage exists in the CFO's buying power. "The CFO approves all software purchases across the organization, but CFOs also buy software for themselves. There's actually one less layer of approval when they're buying their own software, so it is a little easier to replace it when they're the direct buyer," Jacobsohn explained.
His portfolio spans both horizontal finance applications serving all industries and vertical solutions tailored to specific sectors. Construction and manufacturing have attracted his capital in the vertical space. He also tracks opportunities in transportation, logistics and healthcare, though the latter falls outside his primary focus.
The State of Automation in Finance Workflows
Most financial processes have already undergone some form of automation, yet Jacobsohn notes that legacy solutions often handle this work. Some remain on-premise deployments, while others represent companies transitioning from on-premise infrastructure to cloud platforms. He characterizes these as "SaaS 1.0" operations—legacy systems that may only be five to ten years old but lack the AI-native architecture that newer entrants possess.
Specific categories present clearer disruption opportunities. ERP systems dominated by NetSuite and Sage represent one frontier. Sales tax compliance, managed by ancient legacy providers, offers another. Treasury management and procurement round out his areas of focus, with procurement already represented in his portfolio.
AI's Role in Finance: Promise and Peril
Finance teams operate with risk aversion and demand consistency, creating friction around AI deployment in accounting functions. "Finance people are risk-averse, and they need consistent answers. There's some concern that there could be errors with AI, and there are," Jacobsohn said.
The challenge lies in deploying AI judiciously within finance products. "You don't want AI doing calculations because it is not good at math. There are certain workflows it can handle where it doesn't produce precise numbers. But when you need precision, accuracy and calculations, you can't rely on AI for that," he noted.
Attacking HR Software's Weak Points
Displacing core HR platforms from Workday, ADP, SAP, UKG and Dayforce presents formidable obstacles due to switching costs and entrenched relationships. Jacobsohn sees better prospects in secondary products where these suite vendors lack focus. "Those companies have really good distribution. Often, the best distribution wins, not necessarily the best product," he observed.
His investment in Legion Technologies, a workforce management specialist, exemplifies this approach. Though UKG competes in the space, its legacy on-premise origins gave Legion, a cloud-native AI competitor, an opening. Similarly, Elevate operates in benefits—a category where suite players allocate limited resources despite its market size. Jacobsohn previously worked at WageWorks, the legacy incumbent that Elevate is now displacing.
Building Durable Companies in the AI Era
AI accelerates product development but also enables faster copying. Jacobsohn believes the net effect favors company builders. "We're going from products that store data and automate some workflows to really smart solutions that understand, predict and execute work for you. It's changing employees' jobs. Employees can focus on higher-value work and automate some of their tasks with agents that can work really quickly."
Competitive dynamics vary by market segment. Simple horizontal workflows for small businesses face commoditization risk. Complex solutions for midmarket and enterprise customers, especially those requiring deep domain expertise or vertical specialization, remain defensible. "Those solutions would also be really hard to maintain. I'm not seeing much competition from people wanting to build internally at my portfolio companies that are focused upmarket, where you need deep domain expertise."
Exit Strategy in a Softer IPO Market
The IPO environment has improved from pandemic lows but remains constrained. This reality doesn't alter Jacobsohn's investment thesis. "It doesn't impact our interest in funding. Our primary entry point is seed and Series A. I've done some Series B and C deals, so we can be opportunistic at the later stage."
He targets entrepreneurs with deep domain expertise pursuing large markets dominated by legacy players. "We don't worry about the exit environment. At some point, the IPO market will open up more, and maybe that will help us in the future. But more companies get acquired than go public."
Acquisitions represent a legitimate outcome, particularly for early-stage investments. "If a company is acquired for less than $1 billion, it still could be a great outcome for us and the company," he said. The challenge emerges when entering at valuations exceeding $1 billion, where few acquirers operate. Early entry positions Norwest to benefit from sub-billion-dollar exits, where most corporate buyers concentrate their budgets.
The Sales Test Every CEO Must Pass
Jacobsohn's background distinguishes him from typical venture investors. "Something that's different about me from most VCs is that I come from a sales background, and I think the CEOs I back need to be good at sales."
Most founders in his portfolio emerge from product and engineering disciplines, but Jacobsohn views sales capability as equally critical. "You need to be good at selling. You need to sell to customers, partners, investors and employees. Before I invest, I'll go on a lot of sales calls I set up with the CEO to see how good they are at selling."
This assessment directly influences his investment decisions. "When I go on sales calls and people aren't interested in a second meeting, and that's a consistent theme, it often leads me to walk away."
Learning From Failure
Jacobsohn maintains a Failure Museum containing more than 1,500 artifacts from defunct companies and products, all catalogued on his website for ongoing study. The collection reveals a counterintuitive insight: "People are eager to share their successes and their failures. The museum evokes more optimism than one might think. People shouldn't be afraid to take risks. Failure can be a springboard to success."
Read more
Spotify Founder's Health Screening Startup Neko Brings Preventative Medicine to the U.S.
The body-scanning company co-founded by David Ek has arrived in New York with a 300,000-person waitlist and backing from nearly $1 billion in funding.
FieldAI Seeks $700M at $10B Valuation as Robot AI Demand Accelerates
The robotics AI startup is in advanced fundraising talks that would quintuple its valuation from last year, according to sources familiar with the matter.
Tech hiring slows even as employers post record open positions
A surge in IT job listings to three-year highs masks a contraction in actual hiring, with technology sector roles declining and unemployment ticking upward.