Embedded Finance Reshapes Startup Economics While Legacy Banks Struggle to Adapt
Startups are leveraging embedded financial services to unlock new revenue streams and meet consumer expectations for seamless, in-app transactions—leaving traditional banks scrambling to modernize aging infrastructure.
Consumer demand for convenience and speed has catalyzed the rise of embedded finance, a trend that transforms ordinary applications into complete financial platforms. The smartphone era established a new expectation: the ability to conduct transactions and access services from a single device. Embedded finance represents the logical continuation of this evolution, positioning financial capabilities directly within the user experience rather than requiring separate visits to dedicated banking channels.
What began as a specialized innovation has matured into a cornerstone of the modern digital economy, particularly for emerging companies. The scope extends far beyond simple payment processing or basic banking connections—it now encompasses the redesign of entire business architectures and the creation of previously nonexistent revenue opportunities.
Yet established financial institutions face mounting pressure to keep pace. The challenge raises critical questions: what precisely is fueling this transformation, and what do today's consumers genuinely expect?
What's driving adoption?
Convenience sits at the core of embedded finance's rapid expansion. Historical financial transactions required physical presence—standing in queues, managing paperwork, visiting branch locations. The process was time-consuming and cumbersome. Digital transformation eliminated these friction points. Contemporary consumers expect to manage payments, access credit, make investments and purchase insurance directly through applications they already frequent. A single tap accomplishes what once demanded hours of effort.
The financial projections underscore this momentum. According to Bain & Co. and Bain Capital, embedded finance platforms and infrastructure providers will generate revenue climbing from $21 billion in 2021 to $51 billion in 2026. Transaction volumes are projected to reach $7 trillion, accounting for 10% of all U.S. financial transactions.
Technological advancement constitutes another powerful catalyst. A decade ago, establishing banking connections demanded substantial engineering resources and extended implementation timelines spanning months. Contemporary startups can now integrate financial capabilities through Open APIs within days, leveraging platforms such as Stripe and Revolut. This accessibility dramatically reduces both financial investment and technical complexity required for financial feature integration.
Perhaps most compelling is the profit motive. For companies outside the financial sector, embedded finance transcends being merely an added benefit—it functions as a critical revenue generator. Platforms capture a share of transaction proceeds while simultaneously increasing user retention and loyalty. Shopify exemplifies this model: nearly half its revenue originates not from subscription fees but from financial offerings including payment processing and lending products. This mutually beneficial arrangement attracts startups seeking new income sources.
Are traditional banks keeping up?
The competitive landscape reveals significant complications. Conventional financial institutions predominantly rely on infrastructure built during the 1980s. Transitioning to contemporary, API-compatible systems demands enormous capital expenditure alongside substantial operational disruption. Consider an institution managing 30,000 or even 10,000 employees requiring migration to new platforms, coupled with legacy database systems and outdated processes—the digitalization effort becomes extraordinarily complex.
Certain major-tier banks are investing billions to deploy Open API infrastructure. Conversely, many second-tier and long-established institutions are falling progressively behind. Aging leadership, inflexible regulatory frameworks, and extensive cybersecurity compliance requirements impede innovation velocity. Numerous institutions still mandate in-person interactions for routine transactions or operate critical functions through obsolete systems such as voice-based trading. This positions them at a disadvantage against fintech competitors delivering superior user experiences through modern design principles.
Changing customer expectations
Offering traditional products like checking accounts or credit cards no longer satisfies market demands. Consumers increasingly expect "super apps"—integrated platforms delivering multiple financial and nonfinancial services through unified, intuitive interfaces. Contemporary digital banking platforms provide transparent visibility into account balances, precise earnings or losses, and exact currency conversion rates. By contrast, logging into a traditional bank (a documented real-world scenario) may yield responses such as "We'll get back to you with the FX rate for converting dollars to euros," followed by waiting for email correspondence—an experience that feels anachronistic.
Financial institutions need not construct every component independently; collaborative arrangements with other providers represent a legitimate strategy. The essential requirement involves delivering the complete experience within a singular application or web interface. Institutions capable of establishing marketplaces embedded within their applications or websites will advance competitively; those unable to do so will forfeit market position and revenue streams.
Arthur Azizov, founder and investor at B2 Ventures—a private fintech alliance managing a collection of financial and technology ventures including B2Broker and B2BinPay—brings extensive perspective to this landscape. As a serial entrepreneur with more than a decade in the sector, Azizov has driven innovation across liquidity management, trading infrastructure, and payment systems.
Read more
Spotify Founder's Health Screening Startup Neko Brings Preventative Medicine to the U.S.
The body-scanning company co-founded by David Ek has arrived in New York with a 300,000-person waitlist and backing from nearly $1 billion in funding.
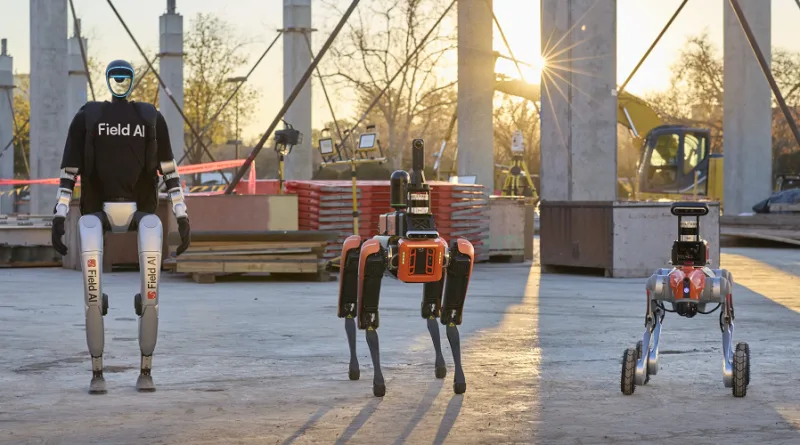
FieldAI Seeks $700M at $10B Valuation as Robot AI Demand Accelerates
The robotics AI startup is in advanced fundraising talks that would quintuple its valuation from last year, according to sources familiar with the matter.
Tech hiring slows even as employers post record open positions
A surge in IT job listings to three-year highs masks a contraction in actual hiring, with technology sector roles declining and unemployment ticking upward.